
After my posts on being broke again at 49 and feeling silently careworn, a few of you let me have it. Irresponsible. Reckless. High of the market psychology.
All truthful factors. Please hold the respectful criticism coming.
I respect the pushback as a result of it compelled me to look exhausting at my threat profile and clarify it out loud. So right here’s my protection. A part of it’s monetary. The opposite half is psychological, and that’s the half virtually no one talks about.
I’ve a liquidity problem. I don’t have a solvency drawback. One makes me annoying at Purple Rocks. The opposite will get your home foreclosed on.
My hope is that this put up additionally will get you to review your own risk profile too. Depart a portfolio alone for a couple of years, and your precise asset allocation can drift removed from what you really need. Rising markets, new commitments, and life modifications all quietly rewrite your threat tolerance for you.
My Enterprise Investing Philosophy Publish FIRE
I left the everlasting labor power in 2012. Since then, AI has accelerated the decline of my capacity to earn supplemental retirement earnings. So the one practical option to outpace inflation is to take a position aggressively till my free money movement runs dry.
And if AI is the largest risk to my earnings, and probably my youngsters’s future earnings, it solely is sensible to personal the very corporations able to ruining our lives. If you happen to can’t beat them, change into an LP.
I’ve been investing since 1996 and have survived multiple bear markets. Throughout the international monetary disaster, I misplaced about 35% to 40% of my web price in roughly six months. Cash that took 10 years of aggressive saving and investing to construct, gone. That have taught me a risk-appropriate asset allocation isn’t non-compulsory. It’s survival.
So I cap non-public investments at 20% of my investable capital. That features enterprise capital, enterprise debt, and angel investing. These investments are opaque, illiquid, and cost larger charges. I’m OK with that. I’m comfortable to pay up for entry to probably larger returns, and I get pleasure from outsourcing the work so I don’t have to consider it.
I additionally cap my non-public and public fairness publicity to 50% of my web price. At my age, I choose much less volatility, no more.
My aim is to outperform the average index investor. You don’t try this by proudly owning solely what the typical index investor owns. On the similar time, my different aim is to remain unemployed till my youngest leaves residence in 12 years.
If 100% of my 20% goes to zero, I’ll be battered however nonetheless survive. Sure, non-public and public markets are correlated, so a foul 12 months for one might be a foul 12 months for each. However ring-fencing a fifth of my capital protects the opposite 80% from my worst instincts. Extra on that beneath.
5 Capital Calls In 5 Weeks
To indicate you the way ferocious the capital calls have been, right here’s a five-week snapshot of each wire I despatched to my enterprise funds.
This will likely even be an ominous indicator of bubble conduct within the non-public markets as an excessive amount of liquidity chases too few promising offers. Venture funds must get bigger to efficiently compete.
5 capital calls in 5 weeks totaling $111,150. That’s far more than my passive income and on-line earnings mixed. Therefore the monetary constraint.
Even a Managing Director at an funding financial institution making $1.5 million a 12 months would wince. An MD’s base wage is about $500,000. Many of the pay comes as a year-end bonus withheld at near 50% in a high-tax state. Then as much as half of that bonus could also be paid in deferred money and inventory that vests over three or 4 years. On paper, $1.5 million. Within the checking account, quite a bit much less.
And this was only one flurry. I’ve had 4 extra prefer it this 12 months, and the 12 months isn’t over. Carrying silent stress is inevitable.
Why Aggressive Enterprise Investing Has Its Advantages
Earlier than making any funding, I spend hours modeling the risk-reward potential and stress-testing my liquidity. Then I assign each funding a selected objective. If I can’t clarify why a greenback goes someplace, it doesn’t go.
Lastly, I speak every funding by means of with my spouse and my father, and generally with the Monetary Samurai group. Three units of eyes catch what one set of overconfident eyes misses.
Right here’s why I’m comfy investing in enterprise so aggressively put up FIRE.
1) It Protects Me From Myself
I’m a horrible dealer. Earlier than 2011, I’d rack up 1,000 trades a 12 months and stroll away up or down $20,000. All that point and stress for a coin flip. My previous massive boss finally flew in from New York to inform me to cease. So I did. Please don’t day trade.
Since then, I’ve largely been a buy-and-hold investor in index funds and particular person shares like Google and Apple. Largely. I’ve nonetheless made some dumb trades that misplaced me loads of cash.
Cash dedicated to enterprise can’t be traded. It’s within the fingers of basic companions who’re incentivized to search out the very best non-public corporations to make their LPs, and themselves, cash.
So I don’t view that 20% as being at better threat. Sarcastically, I view it as being in safer fingers. With GPs incentivized to generate income and lift new funds, I see them as higher fiduciaries than me, who opted out of the grind. Additional, when promoting is one faucet away in your cellphone, the largest threat to your portfolio in a bear market is often you.
2) It Forces Me To Make investments By way of Downturns
In 2009, I wrote that I ought to buy rental properties in Vallejo, California, which was getting obliterated by the financial crisis. I didn’t purchase a single one. Too scared, and an excessive amount of of a PITA. Alternative misplaced.
In 2012, I even tried to sell my primary residence as a result of I feared a housing relapse and I had simply left my day job. Fortunately, no one bid on it. I sold it in 2017 for lots extra.
Enterprise helps with constantly investing, even throughout dangerous occasions. Funds sometimes name about 90% of dedicated capital over three to 5 years, whether or not I really feel courageous or not. When the following downturn hits, I’ll be investing at decrease valuations even when each fiber of my physique needs to hoard money.
Each main S&P 500 decline has finally been adopted by new all-time highs. Understanding that was by no means the exhausting half. Performing on it whereas everybody panics is. Capital calls act on it for me.

3) High Tier Enterprise Corporations Can Generate Superior Returns
Most enterprise capital corporations have not overwhelmed the NASDAQ over the previous 10 years. Nonetheless, the very high tier have and may proceed to take action. Due to this fact, if you may get invited to 1, bounce on the likelihood.
I lastly was in a position to put money into a tier one fund’s 2026 classic after investing of their 2018 and 2022 vintages. Demand was oversubscribed, and I wasn’t going to overlook out on the chance to max out my allocation with them.
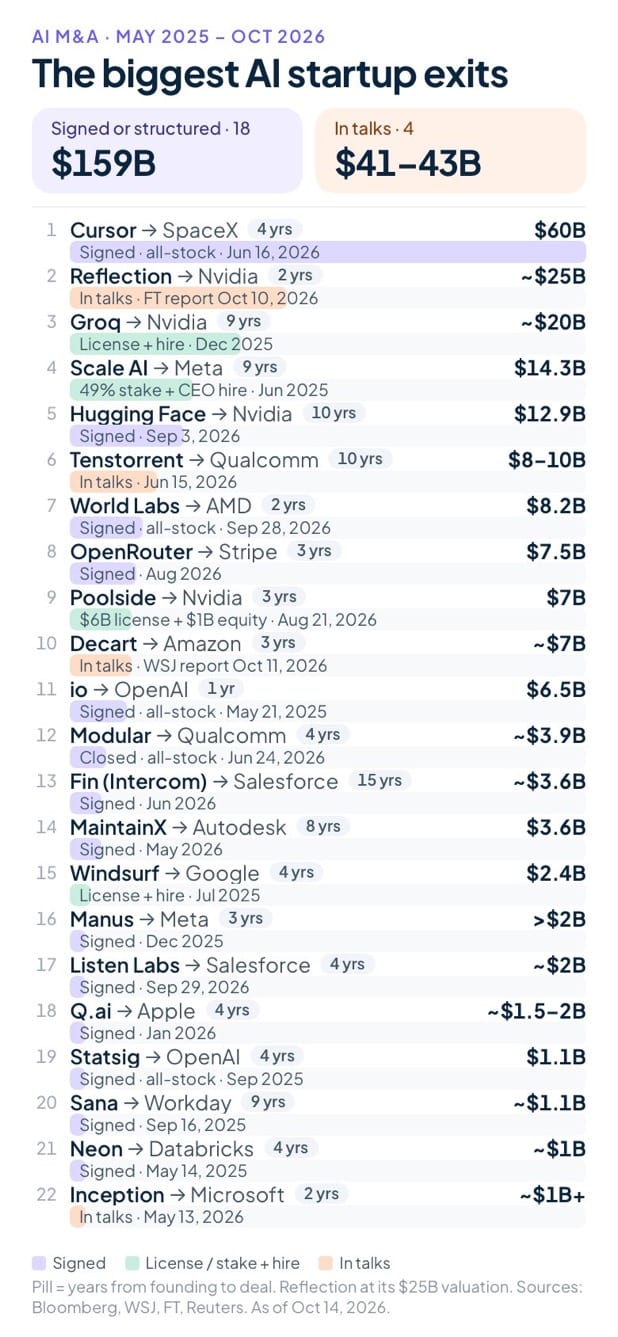
To date, they’re doing properly with investments in names like Intuition and Etched. Nonetheless, these venture returns are not real till they exit. All the identical, the markups really feel good anyway as they hold FOMO at bay.

The Psychology No person Talks About: Sacrifice Feels Good
Now for the half that will get misplaced within the funding allocation debate.
I’m a thrill-seeker. At 18, I acquired in bother with the regulation, largely from taking silly teenage dangers. Afterward, I figured the worst outcomes in life had been going to jail, getting beat up, or getting shot. I’d been in loads of fights, so I may deal with the primary two. I drew the road at getting shot, as a result of I didn’t need my dad and mom to be unhappy.
When your baseline for a foul life is that low, the whole lot else is a win. Touchdown any job is a win. Having a girlfriend is a win. Having the ability to see and listen to is a win. Any cash past primary residing bills is a large win. I’m perpetually grateful to be right here after a tough begin.
That mindset makes taking threat simpler as a result of if I lose, I’m nonetheless in a greater place than I used to be. I’ll admit it may additionally make taking irresponsible threat simpler. That’s precisely why the 20% cap exists.
However right here’s what actually drives me.
There’s little hope for an unemployed previous man like me to make massive cash once more. I had my run: McDonald’s at 15, temp jobs, 13 years in banking, then 17 years writing on Monetary Samurai. All good issues should come to an finish, and I’m at peace with that.
What I’m not at peace with is my youngsters shedding their shot earlier than they even get to take it.
It bothers me when some AI executives gleefully discuss wiping out hundreds of thousands of jobs. They might be proper. However you’d suppose individuals constructing world-changing know-how would know the best way to learn the room. Tens of millions of fogeys are listening, and we’re not amused. These executives should be afraid of the masses, who received’t quit with no battle.
So each time a capital name hits, I really feel worse about my liquidity however higher about my youngsters’s future. That’s a commerce I’ll take each time. As a father, I’d give any a part of myself to assist my youngsters be OK. I am certain each father or mother would too.
The discomfort of feeling broke at this time is outweighed by the hope that the capital comes again in 10 to 12 years, with a return, proper once they’re coming into maturity.
That is the psychological part individuals miss. Sacrifice feels good when it’s for the individuals you’re keen on. Each wire seems like a small act of safety. It’s the monetary model of a father or mother consuming final.
Cash can also be solely half the plan. After college and on weekends, my spouse and I are their homeschool teacher, engaged on expertise which will matter in an AI world. A monetary security web is good. Having the ability to construct your personal is healthier.
Life Is Too Simple And Too Harmful To Depart Up To Your Personal Gadgets
Is a 20% cap sufficient? I’m undecided. Over the long term, the S&P 500 and Nasdaq have been incredible, typically beating different investments. However the temptation to tinker grows the more cash you’ve got.
With $100,000 invested and shares down 20%, you’re in all probability nonetheless working and happy to buy the dip.
With a $10 million portfolio and no job, a 20% decline means $2 million gone in months. That could possibly be a decade of financial savings. That’s when individuals do dumb issues throughout downturns.
That is why I additionally personal actual property. I can’t promote a home on my cellphone simply, so I don’t. That illiquidity is a feature, and it’s the explanation I’ve held some properties for thus lengthy. When values dip, I don’t see a every day quote. And if a neighbor’s sale tells me my house is price quite a bit much less, at the very least I’ve been having fun with residing in it.
Dwelling In America Is Implausible
Having lived overseas rising up for 13 years, I understand how good we’ve acquired it in America. Our freedom, our rule of regulation, and our entrepreneurial spirit give individuals actual hope that tough work results in reward. America isn’t excellent, nevertheless it’s nonetheless the very best nation on this planet for freedom and capitalism. Why not put money into it?
The flip aspect is that consolation makes it straightforward to coast. We overeat and our abs disappear. We binge TV and video video games. Then we get up 10 years later questioning why we don’t have more cash and freedom.
Enterprise capital goes to the guts of the American spirit: entrepreneurship. I wish to again essentially the most pushed individuals taking the largest dangers to vary the established order. On the similar time, I wish to personal loads of the S&P 500, the all-star staff of company America.
Dwelling capital name to capital name is uncomfortable, and I received’t make the identical mistake with my subsequent dedication. However I’ll hold investing aggressively, as a result of I’ve one clear aim: construct as massive a monetary security web as attainable by the point my youngsters change into adults.
Name it reckless if you need. I name it being a dad who thinks in two timelines.
Reader Questions
Is 20% of investable capital in non-public investments too aggressive for a retiree with younger youngsters? What’s your restrict? Have you ever ever invested in one thing partly as a result of it made you are feeling like a greater supplier? And do capital calls make you a extra disciplined investor, or only a extra careworn one?
Get A Free Second Opinion On Your Danger Profile
Depart a portfolio alone for a couple of years, and it drifts. A rising inventory market can quietly flip a 60/40 investor into an 80/20 investor with out them lifting a finger.
In case you have over $100,000 in investable belongings, you may get a free monetary session with an Empower monetary skilled here. Hyperlink your accounts, they usually’ll overview whether or not your precise allocation nonetheless matches the chance you wish to take.
It’s quite a bit cheaper to search out out now than in the course of the subsequent bear market.
Monetary Samurai is a long-time affiliate of Empower and is presently not a consumer.
Learn Extra Books
If you’d like a step-by-step plan for constructing wealth with out shedding your thoughts throughout capital calls, bear markets, or something in between, decide up a replica of Millionaire Milestones: Simple Steps To Seven Figures. I distilled 30+ years of investing and 17+ years of writing right into a roadmap that helps you attain your first million and past, at any earnings degree.
It’s a USA At the moment bestseller revealed by Portfolio Penguin. You may seize a replica on Amazon or wherever you purchase books. Constructing wealth is a marathon, and the precise framework retains you from tripping over your personal toes.
Keep In Contact
Be part of 60,000+ readers and join my free weekly publication here. I write about investing, actual property, enterprise capital, and elevating a household in an AI-driven world, all from firsthand expertise.
To get new posts in your inbox as quickly as they’re revealed, ad-free for the primary few hours, join here.
Cash is just too essential to be left as much as pontification. I’ve been writing from firsthand expertise since 2009, and I’ll hold sharing what I’m seeing and doing with my very own cash.
