
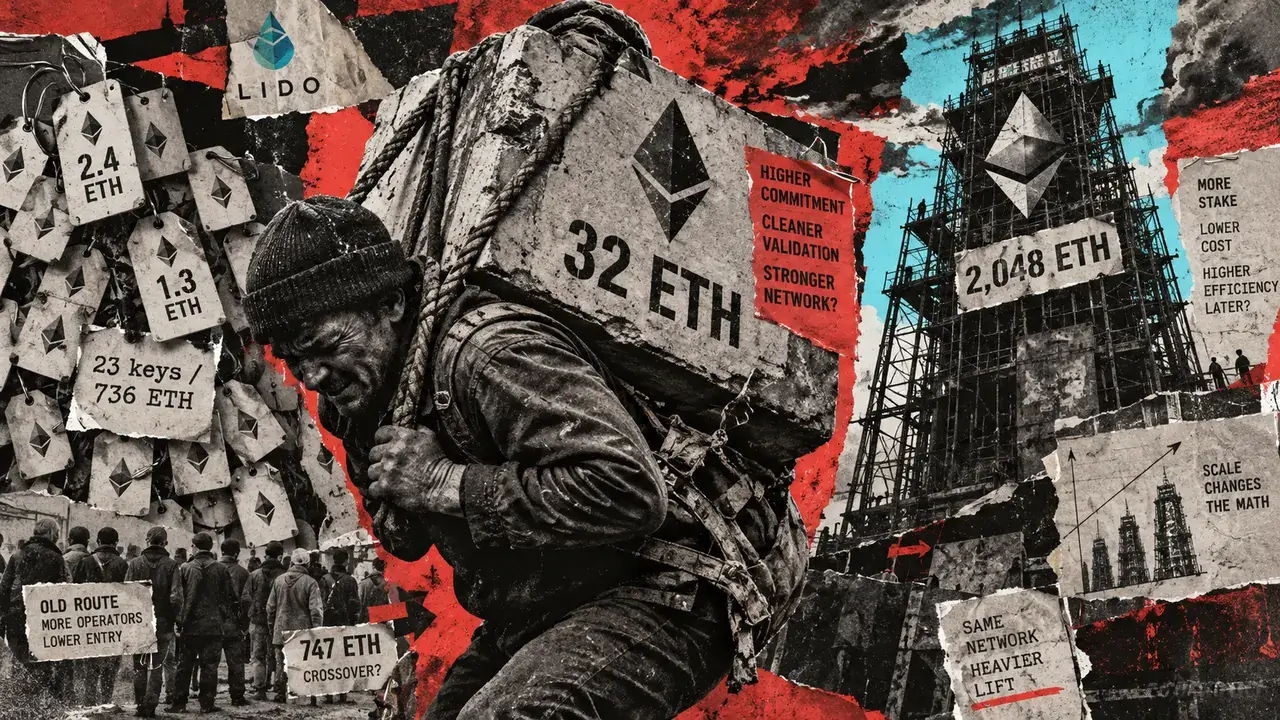
Lido’s proposed route for operating bigger Ethereum validators would require a 32 ETH entry bond, in contrast with 2.4 ETH for its present default route. That increased collateral can turn into extra environment friendly as soon as sufficient stake is allotted to the validator, however an operator’s profile and place within the funding queue decide how helpful the benefit is.
The October 1 deployment plan outlines Group Staking Module 0x02, a separate module for permissionless operators alongside the present 0x01 route. It might help compounding validators with as much as 2,048 ETH of efficient stake, in contrast with 32 ETH for existing-route validators. Every validator is recognized by a key.
The route stays on Hoodi testnet, with mainnet anticipated in This autumn 2026. The deployment submit describes preparations for mainnet and places the module’s Staking Router parameters to a later vote. The July 20 approval of the launch proposal and September 1 testnet announcement have been earlier milestones, fairly than mainnet activation.
Measured as operator charges per ETH bonded, the brand new route reaches parity with a primary present default key close to 747 ETH below equal yield and efficiency. However an operator spreading a 32 ETH price range throughout present default keys raises that modeled threshold to about 1,330 ETH. These are fee-efficiency comparisons earlier than prices, penalties and funding delays.
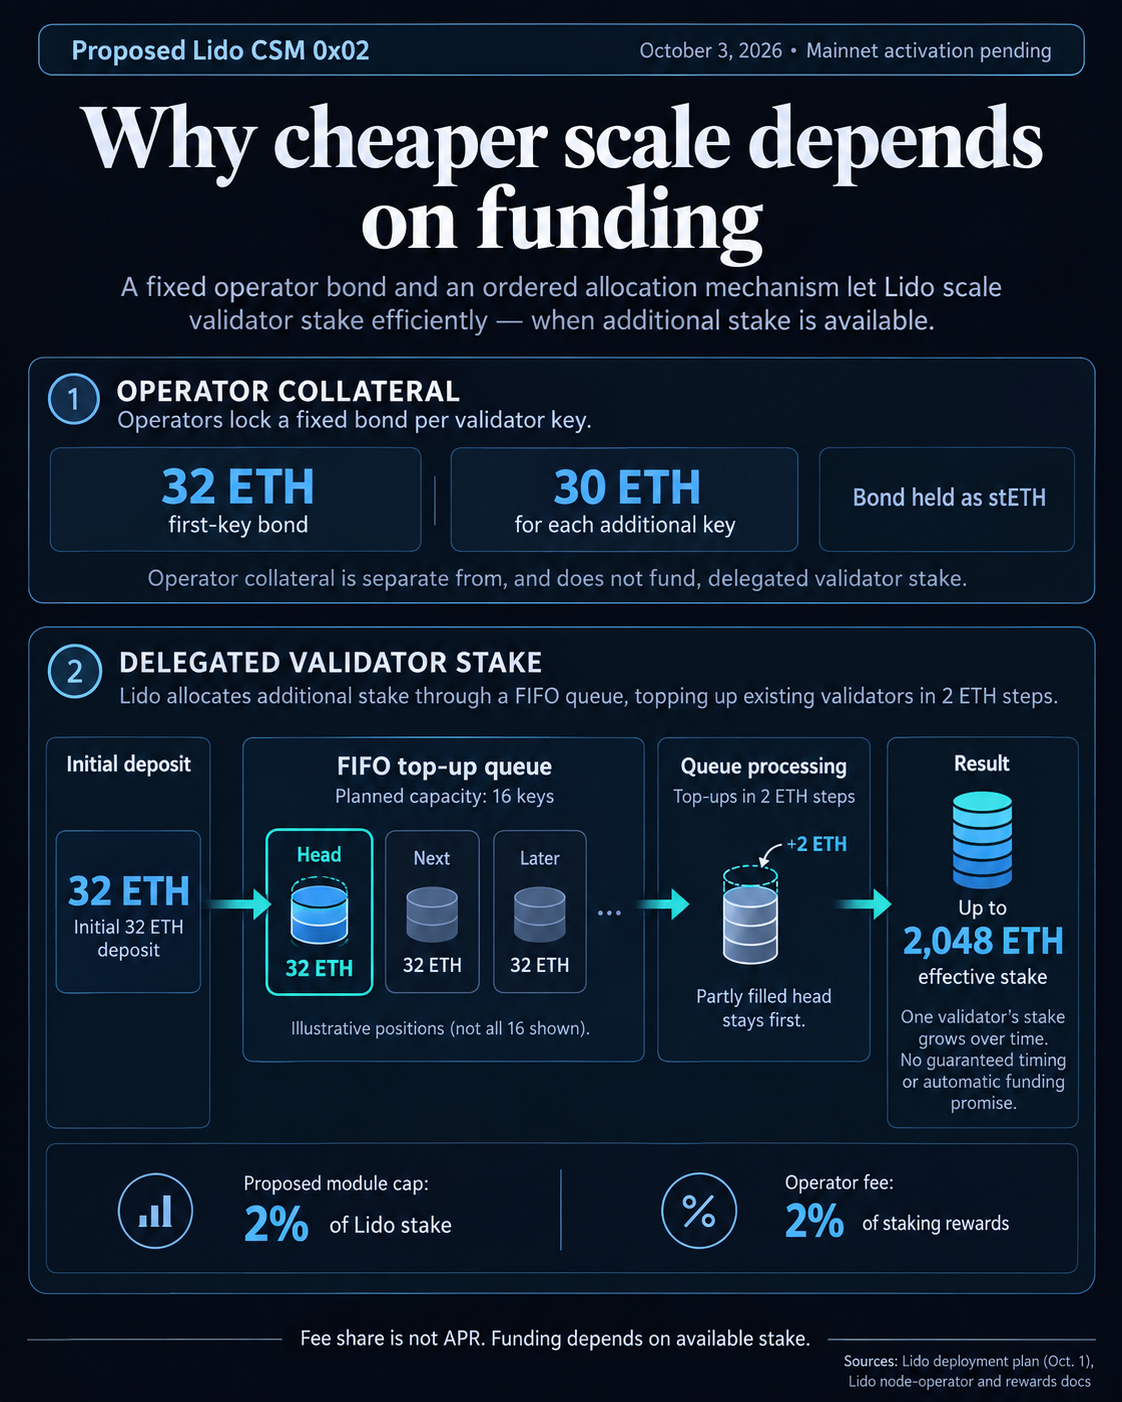
The proposed bond is 32 ETH for the primary key and 30 ETH for every extra key. Underneath Lido’s present 0x01 default profile, the quantities are 2.4 ETH and 1.3 ETH respectively.
The excellence between collateral and stake issues. The bond is the operator’s safety deposit, held as stETH to cowl losses and costs. The protocol provides the validator’s stake individually. Posting a 32 ETH bond doesn’t imply shopping for the validator’s delegated ETH or receiving a assured allocation.
Ethereum’s EIP-7251 permits validators with 0x02 withdrawal credentials to compound, with a most efficient steadiness of two,048 ETH whereas retaining 32 ETH because the minimal activation steadiness. Lido’s bond curve follows the number of keys, so an present 0x02 key would want no extra collateral as its stake grows.
On the most steadiness, the primary key’s bond would equal 1.5625% of delegated stake, or 0.5 ETH of collateral per 32 ETH operated. The next-key ratio can be about 1.465%. These ratios describe a completely funded validator; a key working with solely its preliminary stake has a a lot bigger collateral burden.
Operators would obtain a 2% share of staking rewards, with 8% allotted to the treasury. The deployment setting giving operators 100% of the module charge means they obtain that total 2% slice. It’s neither a 2% staking APR nor a declare on all validator rewards.
Why 747 ETH is simply the primary comparability
CryptoSlate’s calculations under maintain gross staking yield, qualifying efficiency and working period equal. Current-route portfolios are assumed absolutely funded and fee-eligible all through the comparability interval. They examine operator charges earlier than infrastructure prices, fuel, penalties and the bond’s personal stETH returns.
If y is the gross staking yield over the comparability interval and S is efficient stake, proposed first-key charge earnings per ETH bonded is 0.02 × S × y ÷ 32. The prevailing first default key produces 0.035 × 32 × y ÷ 2.4. Equating them provides 746.67 ETH, or roughly 747 ETH.
The 747 ETH determine measures first-key charges per ETH of collateral, utilizing completely different quantities of operator capital. It assumes each validators are funded and fee-eligible for a similar interval.
A 32 ETH price range can as an alternative cowl the bond for 23 present default keys, utilizing 31 ETH of bond and protecting 736 ETH of delegated stake if all keys obtain funding. One proposed-route key matches that portfolio’s whole operator charges at 1,288 ETH. It matches charges per ETH really bonded at about 1,330 ETH, as a result of the present portfolio posts solely 31 ETH.
Verified profiles change the outcome once more. Lido’s operator economics table provides Impartial Group Stakers, or ICS, a 1.5 ETH first bond and 1.3 ETH thereafter, with a 6% reward share for his or her first 16 keys and three.5% after. Verified impartial clusters utilizing distributed validator know-how, or IDVTC, have a 1.5 ETH first bond and 0.5 ETH thereafter, incomes 3.5% for his or her first 64 keys and a couple of% after. These profiles require eligibility; the proposed module has one permissionless profile.
| Current-route profile | Keys and bond inside a 32 ETH price range | Totally funded present stake | New first-key stake for equal charges per ETH bonded |
|---|---|---|---|
| Default | 23 keys; 31 ETH | 736 ETH | About 1,330 ETH |
| Verified ICS | 24 keys; 31.4 ETH | 768 ETH | About 2,022 ETH |
| Verified IDVTC cluster | 62 keys; 32 ETH | 1,984 ETH | 3,472 ETH, above the two,048 ETH ceiling |
The desk divides charges by required bond really posted. Default and ICS portfolios depart 1 ETH and 0.6 ETH unspent. Divide each alternate options by the identical 32 ETH price range as an alternative, and their total-fee crossovers are 1,288 ETH and 1,984 ETH respectively. Returns on spare capital are exterior this fee-only mannequin.
The ICS portfolio subsequently leaves little room under the proposed validator ceiling for a fee-efficiency benefit. The modeled DVT cluster stays forward all through the accessible steadiness vary. Neither outcome establishes web profitability, as a result of the operational setups can have completely different prices.
Further keys additionally want their very own comparability. On the margin, a proposed 30 ETH bond versus an present default 1.3 ETH bond provides a theoretical fee-efficiency crossover round 1,292 ETH, fairly than the first-key 747 ETH determine.
Funding and penalties decide the web outcome
The October plan specifies a 16-position top-up queue. A key first receives its preliminary 32 ETH by the deposit queue, then enters a separate first-in, first-out queue for additional funding.
Underneath Lido’s queue mechanics, top-ups serve the pinnacle in multiples of two ETH, restricted by accessible stake. A partly stuffed key stays on the head till its remaining capability is stuffed. Later keys can not transfer forward for top-ups, and a full queue throttles new preliminary deposits.
The proposed module cap is 2% of Lido stake. That constrains module allocation; it doesn’t promise any operator a full validator.
These guidelines flip a steadiness comparability right into a timing query. An operator that ultimately reaches 2,048 ETH might spend a lot of the comparability interval ready or operating a smaller steadiness. The related determine is common reward-eligible efficient stake over that interval. Current-route keys additionally want funding and activation, so the desk’s absolutely funded portfolios are conditional benchmarks.
Compounding can assist balances develop, however the module proposal itself makes capital effectivity depending on present efficient steadiness, module capability and protocol inflows. A maximum-balance calculation can not set up how rapidly an operator will attain it.
Lido’s reward rules separate operator charges from the stETH rebase earned on collateral. Including bond returns adjustments the total-income comparability. Evaluating returns per ETH bonded requires the identical bond-return price and interval earlier than that stream can cancel out between alternate options.
Efficiency additionally impacts fee. A validator under the edge earns no operator rewards for that body, whereas its bond can proceed rebasing. Lacking collateral should be restored earlier than rewards are claimable.
The proposed configuration makes use of a 28-day body, 3% efficiency leeway and a three-strike threshold with a six-frame strike lifetime. Balance-scaled penalties attain 16.512 ETH for bad-performance ejection and 6.4 ETH for delayed exit at a full 2,048 ETH steadiness. The exit-delay cost follows a four-day deadline and is settled after withdrawal.
A web comparability should add bond returns and subtract infrastructure, fuel and assessed penalties, utilizing precise funded time and reward eligibility. Fewer keys might change working prices, however the parameters alone can not value that distinction.
Forward of mainnet activation and the module-specific router vote, the helpful alerts are the ultimate charge and cap settings, accessible funding and progress by the queue. The proposed route provides default operators a conditional path to higher charge effectivity at scale; verified operators have stronger present alternate options, and the lower-bond 0x01 route continues alongside it.
