
Aave’s proposed institutional lending enterprise would put crypto collateral on either side of the financing chain. Establishments would pledge Bitcoin or Ether for greenback loans, whereas the group governing the Aave lending protocol would initially borrow these {dollars} towards a separate pool of its personal crypto belongings.
Aave Labs’ September 30 clarification identifies an Aave Labs entity because the contractual lender and confirms that the DAO-funded route would pay prevailing Aave V3 stablecoin borrowing charges. That makes the borrower’s potential to satisfy a margin name just one take a look at of the enterprise. The funding place might face its personal collateral strain or rising curiosity prices whereas an institutional mortgage stays present.
Aave’s governing group, the DAO, is contemplating two proposed funding authorizations: a 25 million issuance bucket for GHO, Aave’s stablecoin, and as much as $25 million of USDC or USDT borrowing towards DAO belongings. The scope consists of BTC and ETH. The mixed $50 million request is capability for lending towards BTC and ETH; precise excellent loans stay undisclosed.
Aave Labs stories roughly $300 million of indicated demand and describes a $20 million lead BTC facility. The demand pipeline and lead facility are indicative, with precise drawdowns nonetheless to be reported.
A decline in crypto costs might weaken each collateral swimming pools, whereas rising stablecoin borrowing prices might slim the DAO’s curiosity unfold. The ensuing strain would depend upon the belongings pledged, every place’s phrases and the way shortly institutional mortgage charges might be adjusted.
Two collateral books, two reimbursement obligations
The September 24 proposal would initially fund lending by pledging DAO-owned WETH and WBTC, with AAVE permitted as much as 50% of collateral at every pledge. WETH and WBTC symbolize wrapped Ether and Bitcoin. The DAO would borrow USDC or USDT on Aave V3 and use that financing for institutional services.
Individually, the institutional borrower would place BTC or ETH with a professional custodian. That collateral would safe the borrower’s mortgage beneath a Grasp Mortgage Settlement with an Aave Labs entity. A 3-party Account Management Settlement would join the lender, borrower and custodian.
These are totally different belongings pledged for various money owed. The DAO’s onchain pledge can be separate from the borrower’s custody account. The proposal says borrower collateral would by no means be rehypothecated, or pledged onward.
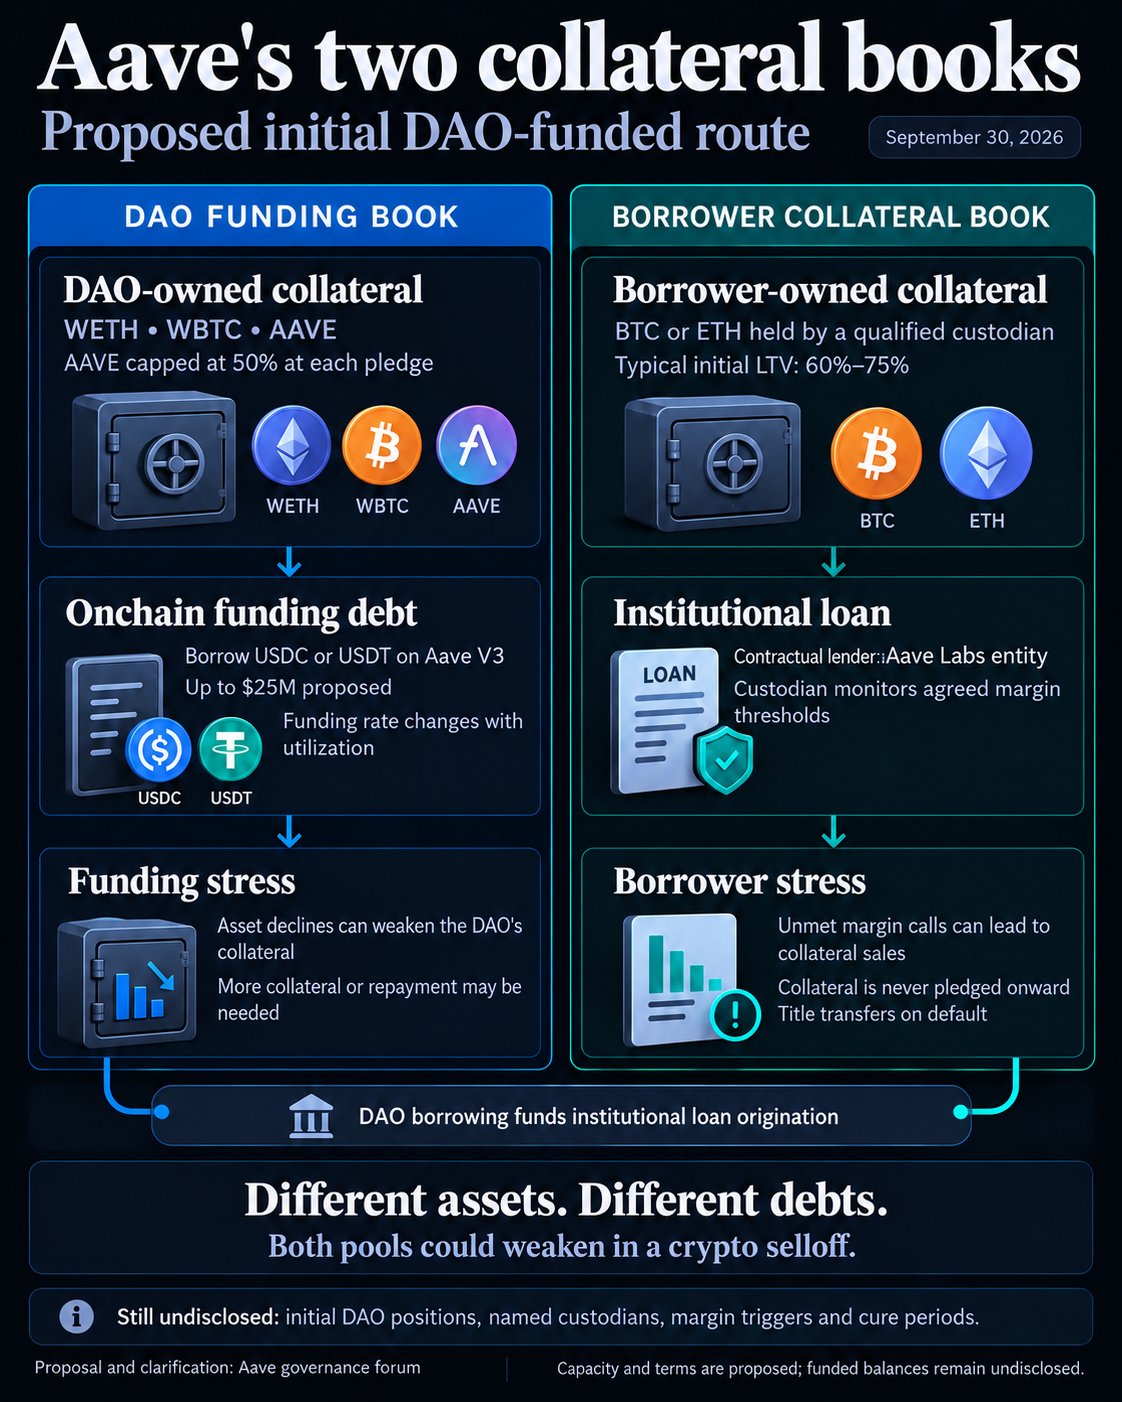
That construction permits an establishment to acquire liquidity whereas retaining its crypto publicity, topic to margin phrases. It additionally leaves the DAO with an onchain debt that has to stay adequately collateralized independently of the establishment’s reimbursement schedule.
The proposed custodian would monitor borrower collateral, difficulty margin calls and liquidate if these calls had been unmet. Authorized safety pursuits and title switch on default are meant to let the lender direct a sale and reimbursement. The paperwork describe how enforcement would work; a report of enforcement beneath these services stays to be reported.
Typical preliminary loan-to-value ratios can be 60% to 75%, in response to Aave Labs. A loan-to-value ratio compares the quantity borrowed with the collateral’s worth. Every facility’s margin set off, remedy interval and liquidation phrases would decide how far collateral might fall earlier than enforcement.
A broad crypto decline might weaken each books. Falling BTC or ETH would enhance strain on an establishment’s custodied collateral, whereas declines within the DAO’s WBTC, WETH or AAVE might cut back the cushion supporting its stablecoin borrowing.
The proposal explicitly acknowledges the chance of AAVE weakening when BTC-backed loans come beneath stress. Its 50% cap limits AAVE’s share when collateral is pledged. Administration of subsequent modifications in that share would sit with the Aave Finance Committee, led by TokenLogic, which might additionally monitor funding-position well being.
Onchain funding additionally has its personal collateral necessities. Aave’s borrowing documentation explains {that a} borrower should keep adequate collateral and monitor its well being issue, a measure of the place’s safety towards liquidation. Extra collateral or partial reimbursement might be wanted as that safety deteriorates.
For the proposed institutional enterprise, this creates a liquidity query earlier than it essentially creates a credit score loss. An establishment may nonetheless be paying its mortgage whereas the DAO must strengthen the collateral securing its funding. Borrower collateral can’t be assumed instantly out there to help the separate DAO place; entry would depend upon the power’s safety and enforcement preparations.
Whether or not such strain would really come up depends upon the preliminary DAO collateral combine, debt measurement, well being elements and facility margin phrases. These particulars haven’t been printed within the proposal and clarification. The construction helps a correlated-stress situation, with the scale and timing of any collateral gross sales depending on these undisclosed positions and phrases.
Floating funding can devour the mortgage unfold
The second take a look at is the price of carrying the loans. Aave Labs offers indicative borrower pricing of 6% to eight% APR towards roughly 4.5% funding prices, implying a 1.5 to three.5 percentage-point curiosity unfold for the DAO.
The September 30 reply makes clear that 4.5% is an indicative price that may change. The balance-sheet route would pay the prevailing V3 price for borrowed USDC or USDT. The GHO-funded route would carry the present price paid to sGHO savers.
Aave charges depend upon pool utilization, which measures how a lot of provided liquidity is borrowed, and on governance parameters. Charges alter as liquidity is borrowed or repaid. A change in inflation expectations or Federal Reserve coverage would subsequently not mechanically set the DAO’s Aave funding price.
The institutional mortgage coupon has a distinct clock. In its September 30 response, TokenLogic says mortgage charges are mounted by contract and might stay stale throughout the discover interval, usually 90 days. The described lead facility is evergreen, with both get together in a position to name it or alter its price on 90 days’ discover.
An illustrative calculation exhibits the publicity. Holding a mortgage coupon on the backside of the proposed vary, 6%, would produce the next spreads:
| Assumed annual funding price | Unchanged mortgage coupon | Curiosity unfold earlier than different prices |
|---|---|---|
| 4.5% | 6% | +1.5 share factors |
| 6% | 6% | 0 share factors |
| 7% | 6% | −1 share level |
The desk illustrates sensitivity to assumed larger funding prices whereas holding the borrower’s coupon unchanged. An increase to six% funding would exhaust the curiosity unfold even when the borrower paid in full. At 7%, the unchanged mortgage coupon can be beneath the price of funds. TokenLogic additionally notes that custody, working, execution and credit score prices nonetheless should be paid, leaving the curiosity unfold to cowl these bills earlier than any revenue.
Shifting towards GHO would change the funding publicity. The preliminary DAO-funded route would keep away from changing GHO into the lending forex or drawing Stability Module stock. The GHO route must convert issued GHO into the {dollars} debtors primarily need whereas managing that conversion’s impact on liquidity and the peg.
The proposal prioritizes matched sGHO inflows, then secondary-market liquidity, with the Stability Module final. That module offers the dollar-stablecoin stock out there for GHO redemptions. The proposal requires conversions to be routed with TokenLogic, sized and timed to market depth, and deferred if they can’t meet an agreed most peg deviation.
Aave Labs reported $59.9 million of Stability Module redemption stock as of September 24. The determine offers a September 24 liquidity reference; the proposal provides no up to date September 30 stock. TokenLogic’s new response says stock is inadequate to help a mortgage of the proposed measurement and period with out liquidity administration.
TokenLogic additionally says matched sGHO inflows should final at the very least so long as borrower drawings. Matching quantities at origination might nonetheless go away a funding hole if the cash supporting a mortgage departed earlier than reimbursement.
Disclosures would present how a lot strain the DAO can take up
The proposal’s printed path stays neighborhood suggestions, adopted by Snapshot if sentiment is favorable and an AIP after a constructive Snapshot. The present dialogue doesn’t disclose a accomplished approval, deployment transaction or stay loan-level reporting.
Every proposed funding authorization would require the GHO Stewards’ two-of-three approval association involving Aave Labs, TokenLogic and LlamaRisk. Aave Labs guarantees reporting on excellent balances, collateral composition, LTV distribution, margin occasions, losses and funding positions. TokenLogic says a future Funding Replace will element the preliminary DAO collateral choice.
The exact lender entity and custodians stay unnamed. Numerical margin triggers and remedy intervals are additionally lacking. The legal-party clarification identifies who would contract with a borrower, however leaves the allocation of losses and enforcement proceeds between that entity and the DAO unresolved.
Exit rights matter alongside these disclosures. Proposed time period loans would mature inside 12 months, whereas evergreen services would usually have notice-based name and repricing rights. Setting GHO facilitator capability to zero might cease new minting, however wouldn’t retire excellent GHO; eradicating the facilitator requires its excellent bucket steadiness to achieve zero.
The ensuing take a look at is broader than whether or not an establishment can keep away from promoting Bitcoin at origination. Aave’s proposed financing might protect that publicity whereas introducing a separate want for the DAO to help its personal collateral and funding prices. The primary funding replace and loan-level report would present whether or not the 2 books have sufficient liquidity and contractual flexibility to resist strain collectively.
